Quick answer
Fit-out finance funds the cost of building out business premises: joinery, counters, kitchens, partitions, lighting, flooring, signage and specialist equipment. Because much of a fit-out is fixed to the premises and has little resale value, lenders often combine it with equipment finance for the movable items, and may want other security or a strong trading case for the rest.
Key points
- Funds joinery, counters, kitchens, lighting, signage and more.
- Fixed items have little resale value, so lenders look at the business.
- Movable equipment is often financed separately.
- Your lease length should cover the finance term.
- Covers
- Joinery, kitchens, partitions, signage, lighting
- Suits
- Retail, hospitality, medical, offices
- Security
- Equipment, property or business strength
- Watch
- Lease term vs finance term
What’s in a fit-out?
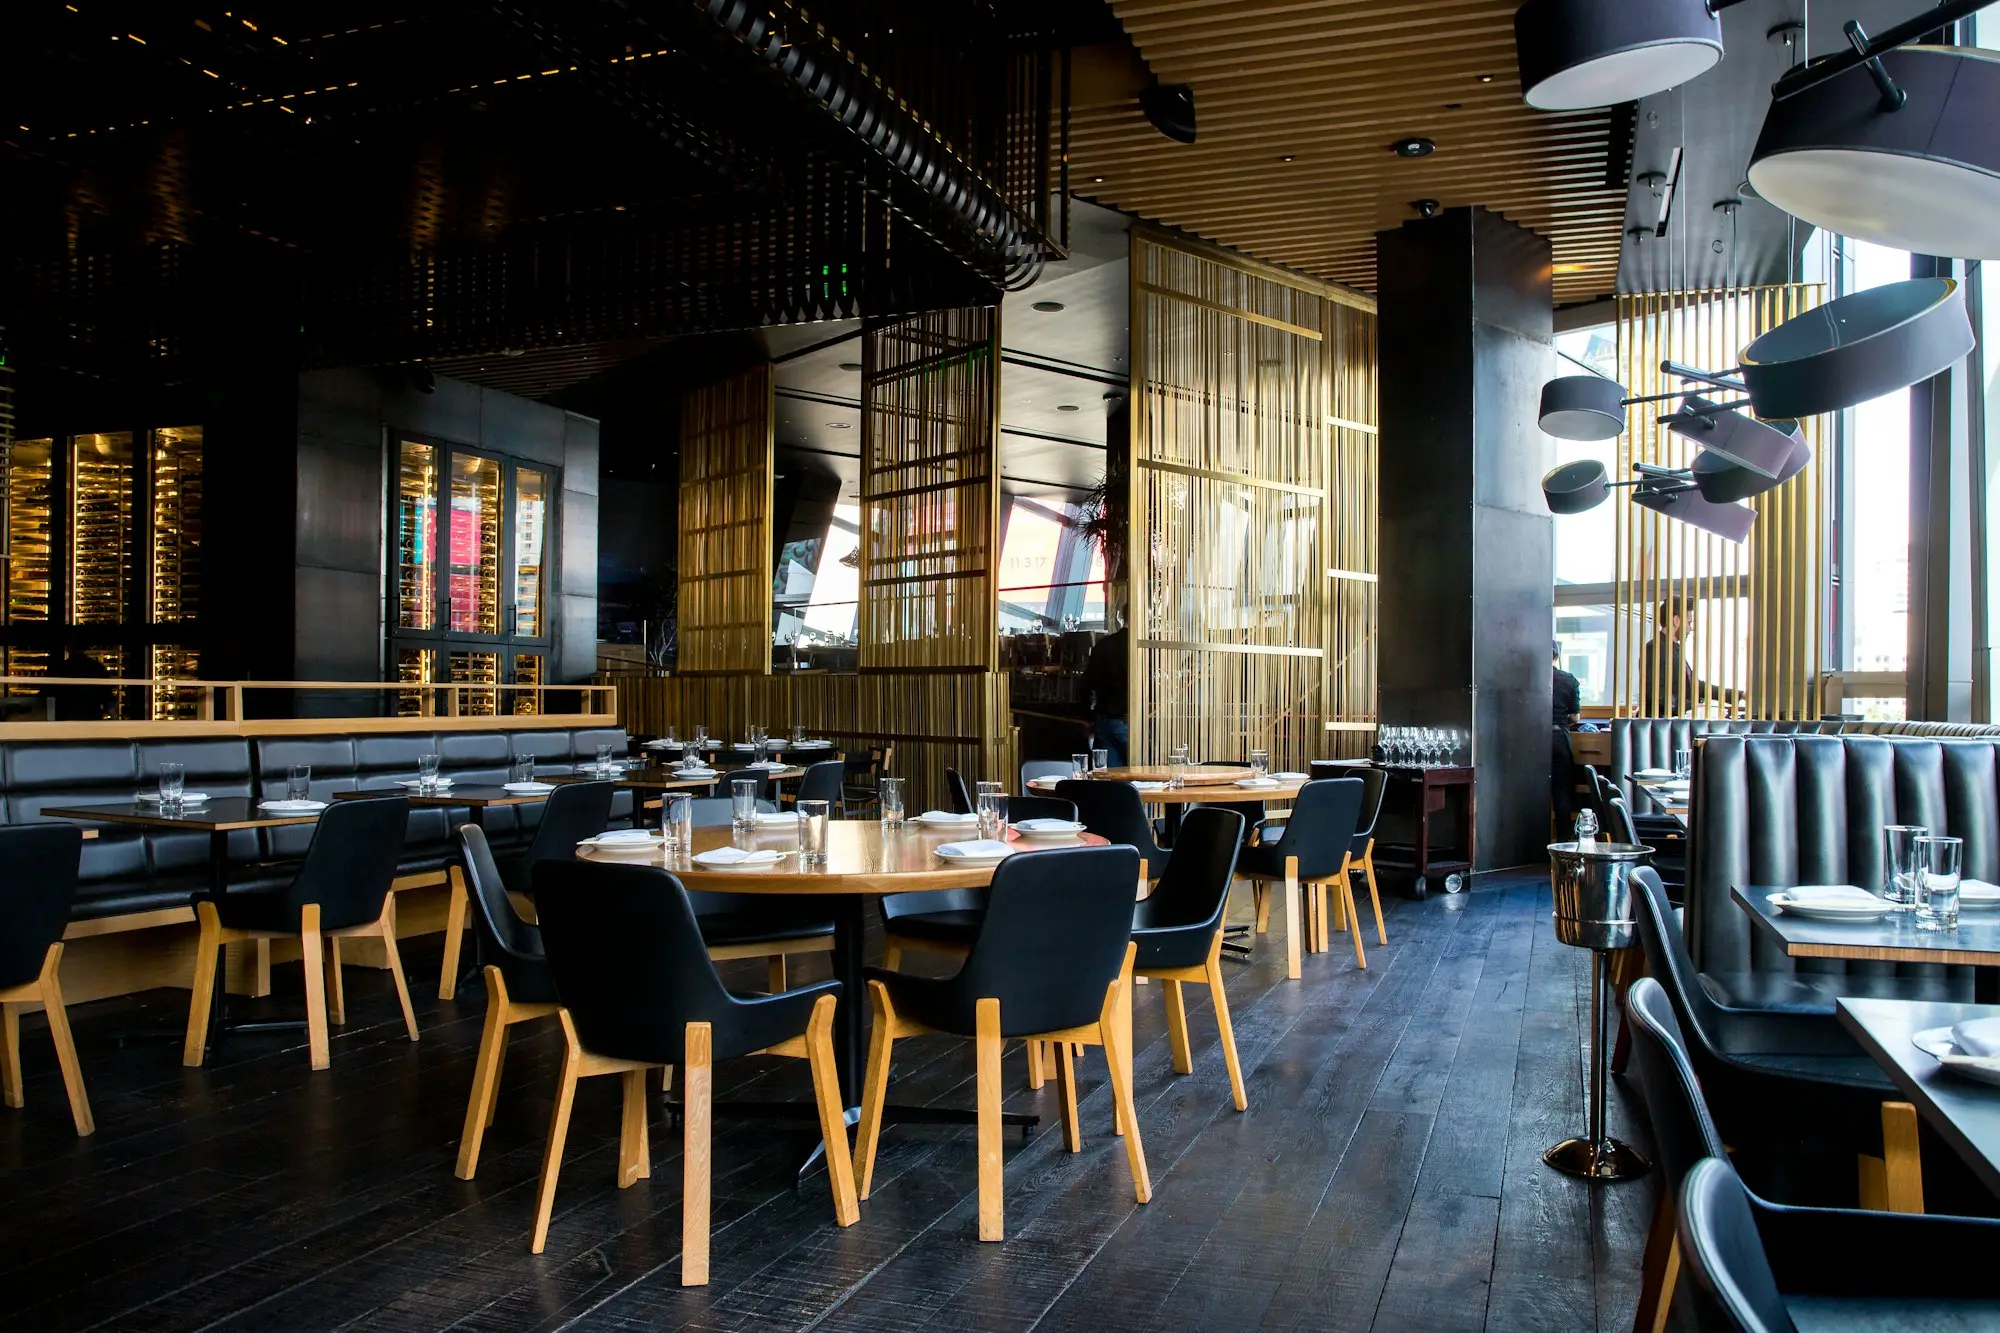
A fit-out turns an empty shell into a working business: a café’s counter and kitchen, a clinic’s treatment rooms, a shop’s shelving and lighting, an office’s partitions and meeting rooms. It’s often one of the biggest costs of opening or relocating.
Splitting the fit-out
| Part | Example | Best funded by |
|---|---|---|
| Movable equipment | Ovens, chairs, fridges, POS | Equipment finance |
| Fixed fit-out | Joinery, partitions, plumbing, electrical | Fit-out loan, property-secured or unsecured |
| Technology | Screens, networks | Technology finance |
Splitting it this way lets each part be financed on the best terms, and reduces the amount that relies on the business alone.
Lease length matters
If your lease ends before the fit-out finance does, you could be paying for a fit-out in premises you’ve left. Lenders want the lease (including options) to cover the finance term. Negotiate the lease with that in mind.
Who uses fit-out finance?
Cafés, restaurants, retailers, gyms, salons, medical and dental practices, childcare centres and offices. Franchisees often have specific fit-out requirements; see franchise finance.
Planning a refit or new site? Tell us about the project.
An illustrative example
A dental practice moves to larger premises. Dental chairs and imaging are financed as equipment; joinery and plumbing are funded through a loan over the lease term. (Illustrative only.)
What else is fit-out finance called?
Lenders, accountants and search engines don’t all use the same words. You’ll also see this entry described as Shop fit-out loan, Office fit-out finance and Refurbishment loan. In our A–Z index every one of those names points back to this page, so whichever term you searched, you’ve landed on the same thing. If a lender uses a name you don’t recognise, ask them to describe how the security, the term and the repayments work; that tells you far more than the label.
Where does it sit in the directory?
This entry lives on the growth and restructuring shelf. It’s most often used for buying, starting or growing a business, equipment and vehicles, and the security usually involved is whatever suits the deal, from nothing at all to property. It usually involves a little more paperwork and assessment than the quickest options, so start early. Its closest neighbours are:
- Rural and farm business loans — Seasonal income, land, livestock and machinery — finance that understands the farm calendar.
- Professional practice loans — Buy into, set up or expand a medical, dental, legal or accounting practice.
- Tradie business loans — Tools, utes, materials and the wait for progress claims to be paid.
- Business acquisition loans — Fund the purchase of an existing business, its goodwill and its stock.
To compare all of them at once, filter the Loan Finder by purpose and security.
Common mistakes to avoid
- Starting with the product instead of the purpose. Decide exactly what the money must achieve, then choose the structure that fits it.
- Not comparing secured and unsecured options. The same need can often be met either way; the right answer depends on amount, credit and timing.
- Under-estimating the total cost. Ask for the full amount repayable in dollars, including every fee, before you compare offers.
- Applying everywhere at once. Multiple applications can leave a trail of credit enquiries. One well-prepared enquiry is better.
- Leaving it until the last minute. Facilities are easier to arrange while trading is strong, not in the middle of a crunch.
What should I ask before signing up for fit-out finance?
A short list of questions saves a lot of regret. Put these to any lender or specialist before you commit:
- Which structures did you consider for me? A good specialist explains why one option beats the others for your situation.
- What’s the total cost in dollars? Compare like with like across secured and unsecured offers.
- What security or guarantees are needed? Know exactly what’s on the line before you sign.
- How are repayments timed? Match frequency to how money comes into your business.
- What happens if things change? Ask about early repayment, top-ups and hardship options.
If an answer is vague, ask again or ask for it in writing. Good lenders are happy to explain their terms clearly.
Build the space your business needs
If you’re fitting out premises, the right structure keeps cash available for opening day and beyond. Enquiring involves no credit check and goes to one specialist rather than a parade of lenders.
Please tell us about the premises, the lease, the fit-out quote and the equipment involved. Accurate details mean a sensible structure. Start your enquiry.
Frequently asked questions
Why is fit-out finance harder than equipment finance?
Fit-outs are largely attached to the building and can't easily be resold, so the lender relies more on the business's ability to repay.
Can I finance a fit-out for leased premises?
Yes, but lenders want your lease to run at least as long as the finance term, and may want to see the lease.
Should I split fit-out and equipment?
Often yes. Equipment like ovens or dental chairs can be financed against itself, leaving a smaller amount for the fixed fit-out.
Will the landlord contribute?
Sometimes. Landlords occasionally offer fit-out contributions or rent-free periods, especially for new leases. Ask during negotiations.